Rethinking retirement income: three mindset shifts that make a difference
Ren Lin,
Head of Client Strategy
Not investment advice. Please refer to the risk disclosures at the bottom of the page
1
Funding retirement is more than building a pension pot. It is about seeking to turn savings into a reliable income people can live on.
2
Planning for later life should reflect the cost of securing income, which can change over time.
3
Investment risk looks different in retirement, especially when people are drawing money regularly from their savings.
Retirement used to follow a simpler script. You stopped work, received a pension, and carried on with a fairly predictable income.
For many people today, that script has changed. Instead of a regular monthly payment, retirees may find themselves with a pension pot and a series of difficult choices. How much can I take? Will my savings last? What if markets fall? Should I lock in some income now, or wait?
These are big questions. How we answer them will shape our daily spending, peace of mind and the standard of living we can maintain over what could be decades of retirement.
That is why retirement income needs a shift in thinking. The challenge is more than how to save; it is how to turn savings into something that feels steady, sustainable and understandable. This is driving many of our conversations with pension providers today.
In retirement, we want freedom, but we also want reassurance.
Think about income, not just the pension pot
A large pension pot can look comforting on paper. But the figure on the statement does not answer the question most people really care about: how much can I spend each month without running out of money too soon?
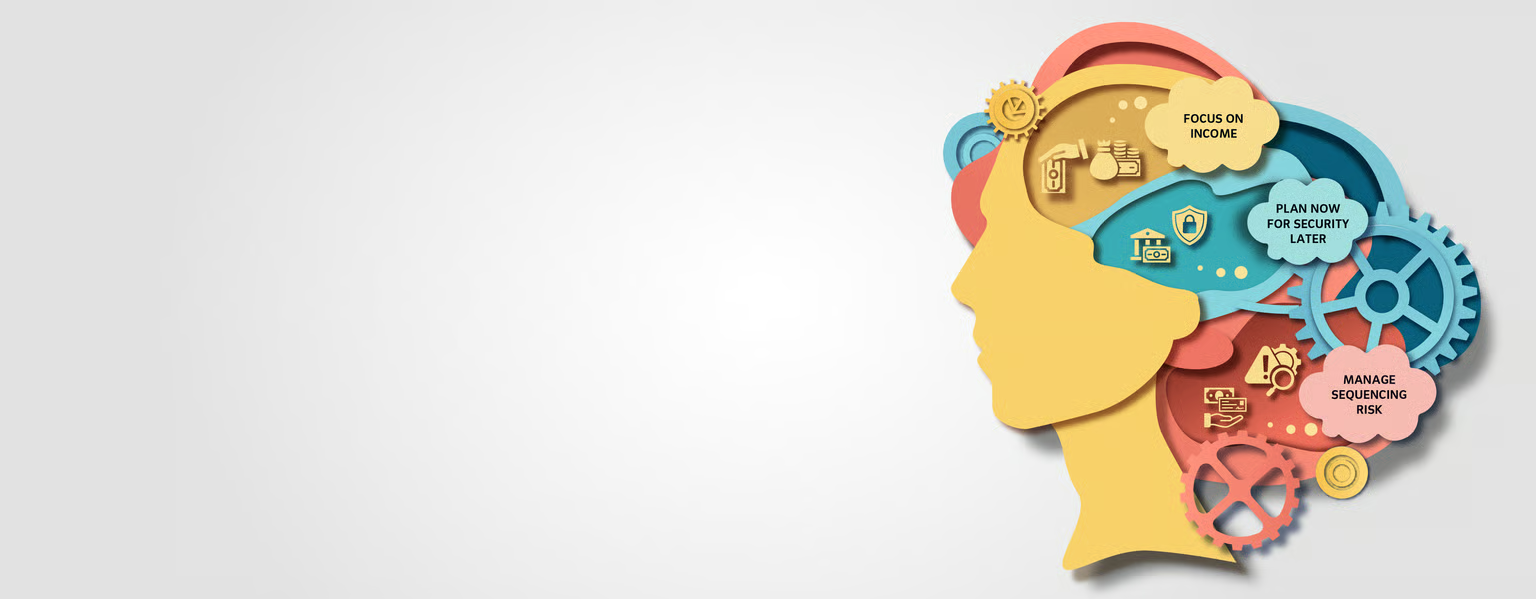
That is the first big shift. In retirement, the focus needs to move from wealth as a lump sum to wealth as a source of income.
This sounds simple, but it changes the conversation. A pot of £300,000, for example, may seem substantial. Yet what matters is how long it needs to last, what returns it may earn, how inflation erodes spending power and whether some of it may later be used to buy an income for life in the form of an annuity1.
Looking only at the total balance can give a false sense of clarity. It tells you what you have today, but not what it can realistically deliver tomorrow.
A more useful starting point is to ask: what income do I need for essentials, what would I like for comfort, and how secure do I want that income to be? That frames retirement in everyday terms. It makes it less about managing a pool of money and more about funding a life.
Plan for security later, not just flexibility now
Many retirees want flexibility in the early years. That makes sense. Spending can be higher at first, while health is better and people are more active. Travel, hobbies or helping family may all take priority.
But later life often brings a different concern: security. At some point, many people place greater value on knowing that a core level of income will keep arriving, no matter what markets do.
This is where the second shift comes in. Even if someone does not want guaranteed income straight away, they still need to think about it early.
One option is an annuity, which turns savings into a regular income for life. Not everyone wants one at the start of retirement, and not everyone needs one. But the future cost of buying that certainty matters. It can rise or fall with interest rates, inflation expectations and insurer pricing.
That means someone can feel richer because their pension pot has grown, while in reality the cost of securing the income they want later has risen even faster.
In practical terms, retirement planning should not treat later-life security as an afterthought. It should be part of the picture from the beginning, and look at how to keep future options open.
Understand that investment risk changes once withdrawals begin
The third shift is about risk. While people are working and still saving, market falls can be painful but manageable. Salary keeps coming in, and there may be years to recover.
Retirement changes that. Once withdrawals begin, bad timing can do real damage.
Imagine two retirees with the same pension pot and the same average investment return over 10 years. If one suffers sharp losses in the first two years while taking income, and the other suffers them later, the outcomes can be very different. The first person may end up worse off because they were drawing money from a falling pot, leaving less invested for any recovery.
This is often called sequencing risk. The term sounds technical, but the idea is straightforward: when losses happen can matter just as much as how big they are.
That is why retirement investing cannot simply mirror saving-stage investing and focus on just growth. We need to seek out potential for growth that supports withdrawals, without exposing the retiree to unnecessary strain.
That may mean holding a cash buffer, reducing the need to sell assets after a market fall, or amending the profile of returns for more stability. There is no perfect formula. But the principle is clear: retirement portfolios need to be built for income as well as returns.
In retirement, we want freedom, but we also want reassurance. Many of us want flexibility today without storing up anxiety for later. The latest developments in global pensions regulations could enable this to be delivered at a scale that has never been previously achieved.
For society, let’s not waste this opportunity. This can be ensured by adopting three clear shifts in thinking: to focus on the income our savings can provide, plan early for later-life security, and treat investment risk differently once withdrawals begin.
Get those three things right, and in our view, retirement starts to look less like a guessing game and in our view more like a plan people can live with.
A new approach to funding our retirement
The challenge is more than how to save; it is how to turn savings into something that feels steady, sustainable and understandable.
Ren Lin is Head of Client Strategy at Insight Investment. His primary focus is developing investment solutions to improve the certainty of attaining future funding outcomes for Insight’s clients.