The pension risk that grows as people live longer
Howard Kearns,
Longevity Director
1
Longevity risk is the possibility that members of a defined benefit pension scheme live longer than expected, raising the cost of paying pensions.
2
This risk could grow as these pension schemes run on for longer and medical progress improves life expectancy.
3
This could be significant for pensions, but new approaches aim to manage this in a simpler, more practical way.
Longer lives are usually seen as a sign of progress. Better healthcare, improved treatment and healthier ageing should be good news. But for UK defined benefit pension schemes, longer life expectancy can create a real financial problem.
That problem is known as longevity risk. In simple terms, it is the risk that pension scheme members live longer than the scheme has planned for. If that happens, pensions must be paid for longer, and the total cost rises.
This matters more now than it once did. Many UK schemes are in better financial shape than they were a decade ago, with most now in surplus, meaning they hold more assets than they need under current assumptions. That stronger position is changing the debate about what schemes should do next.
Instead of moving quickly towards handing over pensions to an insurer or winding up, some schemes are considering running on for longer. In some cases, that could allow them to manage their assets over time and potentially release surplus funds, but a longer time horizon also gives risks more time to emerge. Longevity is one of the most important.
For pension members, living longer is something to welcome. For defined benefit pension schemes, it is also something to prepare for.
What longevity risk really means
Defined benefit schemes promise to pay members an income for life. To work out what that promise costs, trustees and advisers must make assumptions about how long members are likely to live.
No one can know that with certainty. If a scheme assumes that members will live to, say, age 86 on average, but many live to 87 or 88, the scheme could face a higher bill than expected. One extra year of life across a pension scheme may not sound dramatic. In financial terms, though, it can make a meaningful difference.
That is because defined benefit pensions are long-term promises. Small shifts in life expectancy can add up when payments are being made to many members over many years.
Why the risk could become more important
Over the past decade, many defined benefit schemes have worked hard to reduce other major risks. They have adjusted investment strategies, improved funding levels and reduced exposure to interest rate and inflation moves. As other risks come down, longevity stands out more clearly.
There is also a wider reason to pay attention. Future medical advances could lead to fresh gains in life expectancy: progress in treating heart disease, obesity and chronic illness could all have an effect. Even if the pace of improvement is uneven, it would not take a dramatic leap in medicine to change pension costs.
For schemes that plan to run for many more years, a risk that once seemed manageable can become more material simply because the scheme is staying exposed to it for longer.
The cost of getting it wrong
If life expectancy assumptions prove too low, trustees may face some difficult choices.
A scheme that looked comfortably funded could find that its position weakens over time. That may force trustees to seek higher investment returns to close the gap. And higher expected returns often come with higher risk.
This is where the issue stops being abstract. A misjudgment on life expectancy can shape real decisions about funding, investment strategy and end goals. A scheme aiming for greater certainty may end up taking on more uncertainty because one key risk was left open.
The pressure can be even greater for schemes that are thinking about running on rather than locking in benefits with an insurer. The longer the journey, the more valuable it becomes to understand and manage risks that unfold gradually.
Source: Insight Investment. For illustrative purposes only. The funding level is a measure of progress of the pension plan towards being able to afford an insurance buy-out. At 100%, the pension scheme can conduct a buy-out, meaning it can transfer all its assets and liabilities to an insurer. In this illustration, at outset the scheme is 93% funded on a buy-out basis and is targeting a buy-out in 20 years. The scheme is invested 50% in UK government bonds and 50% in corporate bonds and does not hedge longevity risk 1. If longevity follows the scheme's initial best-estimate assumptions, the scheme expects to be 104% funded on a buy-out basis after 20 years.
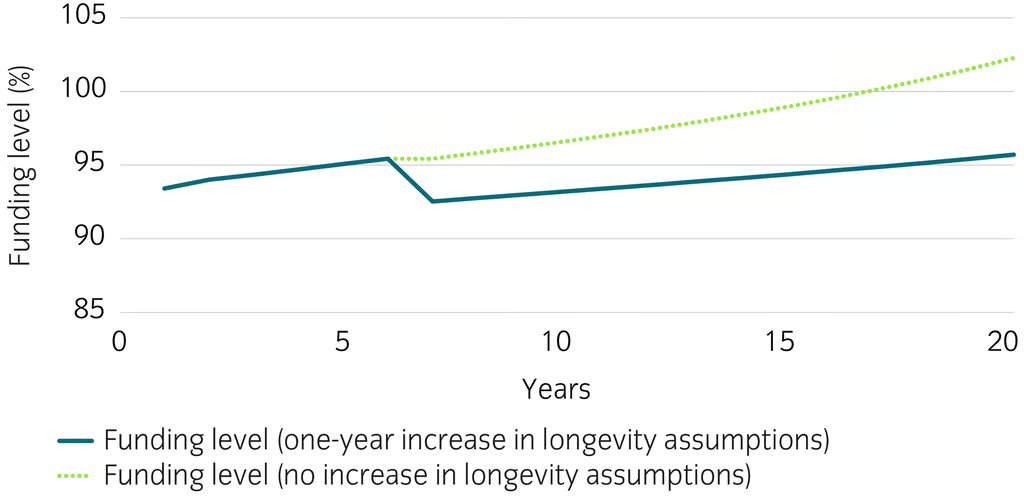
A one-year increase in longevity assumptions can push a pension scheme far off track
Why managing longevity has not always been easy
In theory, pension schemes can protect themselves against longevity risk. In practice, that has not always been straightforward.
One common tool is a ‘longevity swap’. This is a deal that allows a scheme to pass some of the risk of members living longer than expected to another party. But these arrangements have often been highly tailored, expensive and complex to put in place. That has meant they were most often used by the largest schemes, with the scale and resources to handle the process.
At the same time, market conditions have changed. The cost of longevity protection has fallen in recent years, helped in part by lower pricing from reinsurers, which sit behind much of this market. That has made the idea of hedging longevity more practical than it used to be.
Small shifts in life expectancy can add up when payments are being made to many members over many years.
A simpler approach is starting to emerge
This is where a newer approach comes in. Rather than relying on highly bespoke structures, the aim is to make longevity hedging more standardised, quicker to execute and easier for schemes to access. The goal is not to remove every complication from a complex area, but to reduce the barriers that have kept many schemes out.
In plain terms, that could help more defined benefit schemes manage one of their biggest remaining risks without taking on the level of cost and complexity that has traditionally come with it.
Longer lives are good news, but pension schemes still need a plan
For pension members, living longer is something to welcome. For defined benefit pension schemes, it is also something to prepare for.
As more schemes improve their funding and consider running on for longer, longevity risk is likely to become harder to ignore. It may not be the noisiest risk in pensions, but it can have serious consequences if assumptions turn out to be wrong.
The challenge is not simply to recognise the risk, but to manage it in a way that is practical, proportionate and realistic for more schemes than before.
Howard Kearns is Longevity Pricing Director at Insight Investment.
He is responsible for developing Insight’s longevity pricing and structuring capabilities.